
Bear Put Spread: A Defined-Risk Bearish Strategy
JustWolves is an educational platform and is not a SEBI-registered investment advisor. Trading financial instruments involves significant risk of loss and may not be suitable for all investors. Past performance is not indicative of future results. Read our full disclaimer →
What you'll learn
- A bear put spread buys a put and sells a lower-strike put with the same expiry
- Maximum loss = net debit; maximum profit = strike difference − net debit
- Breakeven = higher strike − net debit
- It suits a moderately bearish view with a target near the lower strike
- It's the mirror image of the bull call spread
In this article · 16 sections
The bear put spread is the bearish counterpart of the bull call spread. You buy a put and sell another put at a lower strike, which cuts the cost and the breakeven distance but caps the profit at the lower strike. It's a common way to express a moderately bearish view, or to hedge, without the full cost and decay of an outright put.
What You Will Learn
- How a bear put spread is built
- Maximum profit, loss and breakeven
- Choosing strikes and expiry
- How it compares with buying a put
Before You Start
Read Bull Call Spread first; this lesson mirrors it.
How It's Built
- Buy one put at a higher strike (often ATM).
- Sell one put at a lower strike (OTM), same underlying and expiry, same quantity.
- Pay a net debit: the bought put's premium minus the sold put's premium.
The Numbers
| Measure | Formula |
|---|---|
| Net debit | Premium paid − premium received |
| Maximum loss | Net debit (at or above the higher strike at expiry) |
| Maximum profit | (Higher strike − lower strike) − net debit (at or below the lower strike) |
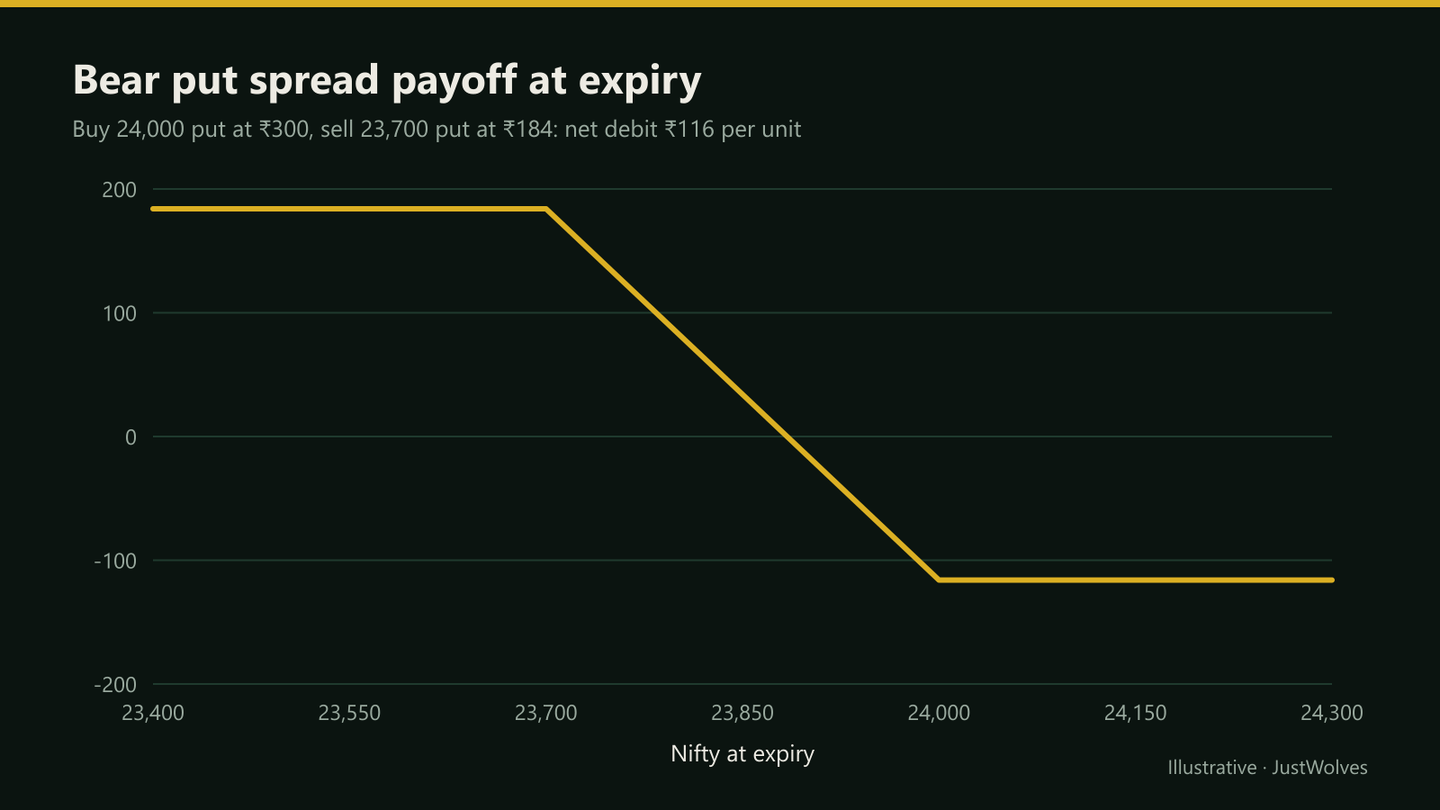
| Breakeven | Higher strike − net debit |
Compared with Buying a Put
| Long put | Bear put spread | |
|---|---|---|
| Cost | ₹300 | ₹116 |
| Breakeven | 23,700 | 23,884 |
| Profit at 23,700 | ₹0 | +₹184 |
| Profit at 23,200 | +₹500 | +₹184 |
| Maximum loss | ₹300 | ₹116 |
As with the bull call spread, the spread does better for moderate moves and the outright put does better for large ones. In index options, OTM puts often carry higher implied volatility than ATM ones, so selling the lower put recovers a relatively expensive premium.
Choosing Strikes and Expiry
- Higher (bought) strike: ATM or slightly ITM.
- Lower (sold) strike: near a realistic downside target, such as a support level.
- Expiry: enough time for the decline to unfold.
Managing the Trade
As with any debit spread, the full profit usually arrives only near expiry, because the sold put keeps some time value while the market sits near the lower strike. Many traders close the spread once it has captured most of its potential value, or once the market reaches their target support level.
If the bearish view is invalidated, for example by a strong close back above resistance, closing both legs together usually recovers part of the debit. Holding to expiry hoping for a turn risks losing it all.
Real Prices: Right Direction, Different Results
The chart below follows a bear put spread through a real month of NIFTY 50 prices in April and May 2026, a period when volatility was unusually high, with the bought put alone shown for comparison. Option values are modelled each day; the index moves are real.
Real NIFTY prices: a bear put spread when volatility was high, April–May 2026
Step 1 of 4
Expensive puts
On 10 April 2026 NIFTY closes at 24,051 after weeks of large swings; modelled volatility is about 33%. The 24,050 put expiring on 13 May costs about 874 points (₹56,810 per lot). A bear put spread, selling the 23,750 put against it, costs just 141 (₹9,165).
- What to observe
- High volatility makes the outright put very expensive.
- Condition
- The spread recovers most of that cost.
How the Greeks Change
Like the bull call spread, the bear put spread has smaller Greeks than an outright put. Its negative delta is smaller, so it gains less per point in the early part of a decline. Its time decay and volatility sensitivity are smaller too, because the sold put offsets part of the bought put's exposure.
That makes the spread more forgiving if the decline takes a little longer than expected, or if implied volatility falls after the move starts, two situations that commonly hurt outright put buyers. The cost of that forgiveness is the capped profit below the lower strike, which is why the lower strike should sit near a realistic target rather than far beyond it, where it would only add cost.
Practical Example
Hypothetically, Nifty is at 24,000 after failing at resistance, with support near 23,700. Swati buys one lot of the 30-day 24,000 put at ₹300 and sells one lot of the 23,700 put at ₹184. Her net debit and maximum loss are ₹116 × 65 = ₹7,540.
Her maximum profit is (300 − 116) × 65 = ₹11,960 at or below 23,700, and her breakeven is 23,884. Two weeks later, Nifty is at 23,750 and the spread is worth about ₹158; she closes for a profit of (158 − 116) × 65 = ₹2,730, choosing not to wait for the final days.
Spread or Put? Our Two-Year Test
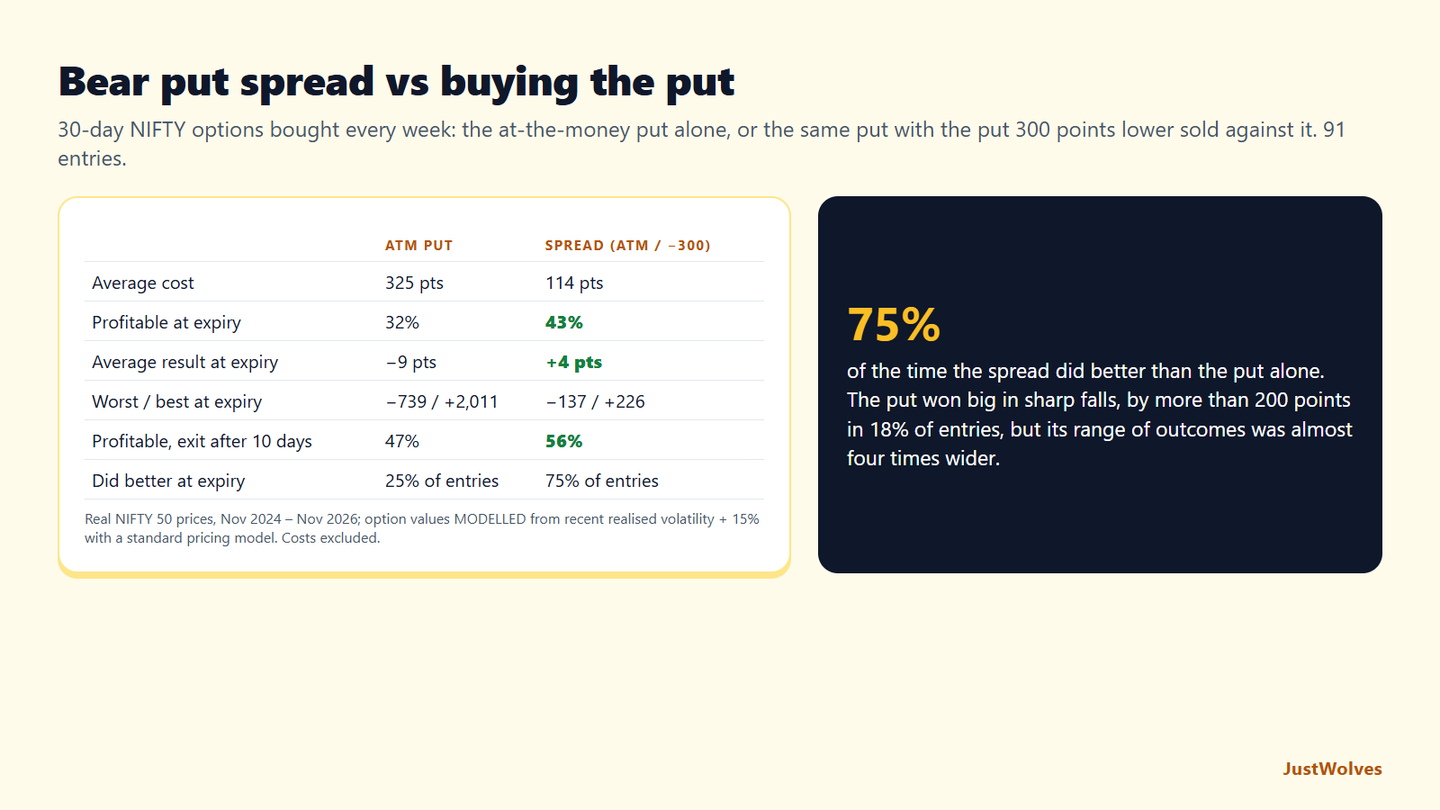
JustWolves tested this lesson's comparison on about two years of real NIFTY 50 prices (November 2024 to November 2026). Each week we bought an at-the-money put with about 30 days to expiry, and separately the same put with the put 300 points lower sold against it, with values modelled from recent volatility. We compared them at expiry and when closed after 10 trading days; 91 entries in all.
| ATM put | Spread (ATM / −300) | |
|---|---|---|
| Average cost | 325 points | 114 points |
| Profitable at expiry | 32% | 43% |
| Average result at expiry | −9 points | +4 points |
| Worst / best at expiry | −739 / +2,011 | −137 / +226 |
| Profitable when closed after 10 trading days | 47% | 56% |
| Did better at expiry | 25% of entries | 75% of entries |
The spread did better than the put in 75% of entries, was profitable more often, and its range of outcomes was about a quarter as wide. The outright put did better in sharp falls, beating the spread by more than 200 points in 18% of entries, such as the February–March 2026 decline, when single puts gained up to 2,000 points.
The chart above shows the other side: when volatility is high, the outright put can lose even when the market falls. In April 2026, with modelled volatility near 33%, the at-the-money put cost more than six times the spread. As this lesson's comparison section notes, selling the lower put recovers part of an expensive premium. Our data cannot show the real volatility skew between strikes, because the model uses one volatility for all of them; in the market, the sold put is often priced even richer, which would favour the spread further.
Closing early worked better here than for bull call spreads. Closed after 10 trading days, the spread was profitable 56% of the time. Several falls in this period were fast, which may explain part of it: a spread opened just before one could capture much of its value within two weeks.
Common Mistakes
- Choosing the lower strike far beyond any realistic target.
- Selling the lower put first when entering.
- Expecting full profit before expiry.
- Using it for crash protection, which it doesn't provide below the lower strike.
- Forgetting costs on both legs.
Professional Insight
Professionals often use put spreads rather than single puts for hedging and bearish views, because downside index puts tend to be priced with a volatility premium. Selling the lower put reduces the cost of that premium while keeping protection over the most likely range.
Risk Considerations
- The net debit can be lost.
- Profit is capped below the lower strike.
- Execution risk on two legs.
Important Terminology
| Term | Meaning |
|---|---|
| Bear put spread | Long higher-strike put, short lower-strike put. |
| Net debit | Net premium paid. |
| Volatility skew | Higher IV on OTM puts than on ATM options. |
| Debit spread | A spread opened for a net payment. |
| Spread width | The difference between the strikes. |
What is a bear put spread?
A strategy that buys a put and sells a lower-strike put with the same expiry, for a net debit.
What is the maximum profit?
The difference between strikes minus the net debit, reached at or below the lower strike at expiry.
When should I use a bear put spread?
When you expect a moderate fall to around the lower strike.
Is it better than buying a put?
It's cheaper with a closer breakeven, but caps profit. A single put does better in a large fall.
Can I use it as a hedge?
Yes, for moderate falls. It doesn't protect below the lower strike.
How often does a bear put spread make money?
In our test of 30-day NIFTY spreads, at the money and 300 points lower, on two years of real prices with modelled premiums, the spread was profitable at expiry in 43% of entries and in 56% when closed after 10 trading days. Costs were excluded.
Why can a bought put lose money when the market falls?
Because the fall has to be larger than the premium paid. When volatility is high, puts are expensive: in a real NIFTY month we modelled, an at-the-money put cost 874 points and still lost money although the index finished 638 points below the strike.
Practical Exercise
Build a bear put spread.
Your task
Step 1: Find a bearish setup
With a clear support target.
Step 2: Choose strikes
ATM bought put; sold put near support.
Step 3: Calculate
Net debit, maximum profit and breakeven per lot.
Step 4: Compare
With buying the ATM put alone at three expiry prices.
Check Your Understanding
A bear put spread sells:
Related Lessons
Previous: Bull Call Spread. Next: Long Straddle and Long Strangle.